Looking for today's Chicago mortgage rates, or a Chicago mortgage broker who actually knows the city? Chicago is a market of neighborhoods, and its housing stock — lakefront and Loop condos, classic two-flats and three-flats, brick bungalows, and single-family homes — makes financing here more specialized than most buyers expect. Add some of the highest Cook County property taxes in the country and a multi-year reassessment cycle, and the right loan really does depend on the block you are buying on. Compare live rates below, price your real numbers with no credit pull, then work with a local broker who shops conventional, FHA, VA, and jumbo loans across many lenders to fit your file.
Live from our pricing engine for a sample scenario. Your actual rate depends on your price, down payment, credit, and property type, so see your real number in about thirty seconds, with no credit pull.
Sample scenario: $520,000 loan on a $650,000 home (jumbo priced as a $900,000 loan), 20% down, 780–799 credit, 30-year fixed, primary residence, Chicago, 30-day lock. Pricing effective 11/18/2026. Rates shown are illustrative, not a rate lock or approval.
●Chicago rates and local data reviewed and updated November 18, 2026 by the licensed Illinois mortgage team at Gateway Capital Mortgage · Company NMLS #246585 — a licensed Illinois mortgage broker that prices Chicago condos, two-flats and self-employed files every week. Rated 4.9★ across 310+ reviews, BBB A+ accredited.
What to know about the Chicago housing market
$420,000Median sale price (+6.3% YoY)
~2.08%Effective property-tax rate
$832,7502026 conforming limit
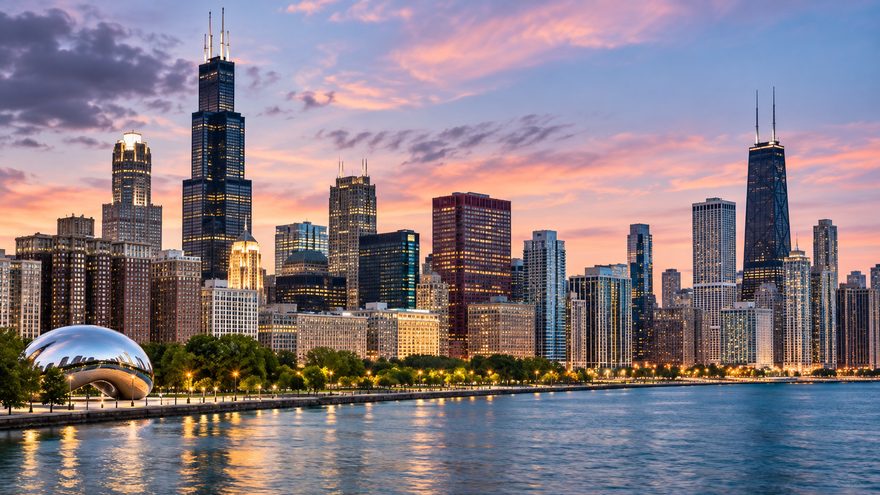
The Chicago skyline and Cloud Gate at sunset. We finance condos, two-flats, and single-family homes across the city and the near suburbs.
Chicago offers something increasingly rare among big cities: real value and genuine variety. From condos in the Loop and along the lakefront to bungalows on the Northwest and Southwest sides to two-flats in the classic neighborhoods, there is a wide range of price points and property types, and each finances a little differently. The market rewards buyers who understand the property type they are buying and come in with financing shaped to fit it.
Because we shop many wholesale lenders instead of pushing one bank's product, we can match the loan to the property and the buyer: the first-time condo buyer in Lakeview, the two-flat house-hacker in Logan Square, the single-family move-up in Beverly, or the self-employed buyer whose returns understate income. One bank has one box. We find the lender that fits.
Condos and warrantability
Condos are a huge share of the Chicago market, and financing them depends on the building as much as the buyer. A building's warrantability, its reserves, owner-occupancy ratio, any litigation, and pending special assessments all affect whether and how a lender will lend on a unit. Some buildings are non-warrantable and conventional financing simply cannot touch them. We work with lenders that handle both, and before you commit we can help you read a building's financial picture so a special assessment or reserve problem does not blindside you.
Two-flats, three-flats, and house-hacking
The classic Chicago two-flat and three-flat is one of the best wealth-building tools in the city. On a two-to-four-unit building you can often use the expected rental income to help you qualify, and if you live in one unit you can buy with owner-occupied financing, including low-down-payment options, while tenants help cover the mortgage. It is a strategy we set up all the time, and getting the rental-income calculation and the right loan program correct is where it succeeds or fails. See our conventional and FHA loan options, both of which allow owner-occupied 2–4 unit purchases.
2026 Chicago & Cook County loan limits
Your loan amount decides your program. At or under the conforming limit you have conventional and government options; above it you are in jumbo territory with its own guidelines. These are the 2026 limits for a one-unit home in Cook County.
Cook County 2026 loan limits, 1-unit
Conventional and VA follow the 2026 conforming limit; FHA is set lower, which matters for lower-down-payment buyers.
*VA has no loan cap with full entitlement; the conforming figure is shown for reference. Source: FHFA / HUD, 2026. Multi-unit limits are higher.
Property taxes, transfer taxes, and the real monthly payment
Logan Square at sunset — the #5 neighborhood in the list below, and the starting price in the calculator. It is one of the city's most popular areas for classic two-flats and first condos.
Cook County property taxes are high, run on a multi-year assessment cycle, and are a big part of the monthly payment, so a realistic figure belongs in your qualification from the start. Illinois carries roughly a 2.08% effective property-tax rate, among the highest in the nation. Chicago also levies a real property transfer tax at closing. Homeowner and other exemptions lower the bill on a primary residence, and many owners appeal their assessments. We build accurate taxes into your estimate and flag transfer-tax costs so nothing surprises you at the table.
Chicago median home price by neighborhood
Ten popular Chicago neighborhoods, ranked by median sale price from highest to lowest. The calculator below starts at #5, Logan Square, as a representative mid-market Chicago price, so change the home price to match the area you are shopping.
1Lincoln Park$845,000
2Wicker Park$725,000
3Lakeview$600,000
4Gold Coast$565,000
5Logan Square ← calculator start$545,000
6Avondale$460,000
7West Loop$430,000
8Bronzeville$350,000
9Hyde Park$315,000
10Rogers Park$245,000
Approximate median sale prices, late 2026, compiled from Redfin and Zillow neighborhood data. Neighborhood medians move month to month and vary by property type (condo vs. single-family); ask us for today's figure on a specific area.
What a Chicago payment actually looks like
Taxes and insurance are a big slice here, not a rounding error. Move the sliders to see your own breakdown, priced live off our engine on Illinois tax and insurance data.
Est. monthly payment —
Principal & interest
—
Property tax
—
Home insurance
—
Mortgage insurance (PMI)
—
Loan amount
—
Live estimate from our pricing engine; PMI applies under 20% down. Illustrative, not a rate lock or approval. See your real rate with no credit pull.
See your real Chicago rate and paymentAbout 30 seconds · no credit pull · no obligation
Chicago is a strong first-time-buyer market, with FHA, low-down-payment conventional, and Illinois and city assistance programs all in play, often paired with a condo or two-flat as the entry point. Programs like IHDA (Illinois Housing Development Authority) down-payment assistance and city first-time-buyer help can be layered with the right loan, and eligibility usually turns on income limits and a homebuyer-education course. We price the options side by side and show the real monthly payment and cash to close so your first purchase is a confident decision, not a guess. See our first-time buyer guide and closing-cost breakdown.
Locking your rate: when it makes sense
Two files with the same credit can land on different rates, because rate depends on your loan-to-value, property type, occupancy, loan amount, and the day you lock. When rates are easing, some buyers float; when they are jumpy, locking removes the guesswork. We walk you through lock-versus-float, whether a temporary buydown or paying points pencils out for how long you will keep the loan, and the real cost of waiting, so the decision is math, not a gut call.
Where we help across Chicagoland
North Side: Lincoln Park, Lakeview, Logan Square, Uptown, and Rogers Park. Northwest and West: Irving Park, Portage Park, and the western neighborhoods. South and Southwest: Bridgeport, Beverly, Hyde Park, and the bungalow belt. Near suburbs: Oak Park, Evanston, Cicero, and the close-in Cook County communities.
Whether it is a first condo in Lakeview, a two-flat in Logan Square, a bungalow in Portage Park, or a single-family in Beverly, the right loan and lender differ for each, and comparing them is what we do.
GC
Gateway Capital Mortgage
Licensed Illinois Mortgage Broker · Company NMLS #246585
This page is maintained and reviewed for accuracy by our licensed Illinois mortgage team, who price and close Chicago loans, condos, two-flats and self-employed files included, every week. Have a scenario or a specific building in mind? That is exactly the kind of question to send over.
In most cases you do not pay a Chicago mortgage broker out of pocket. Broker compensation is usually paid by the wholesale lender and disclosed on your Loan Estimate, or in some scenarios paid by you when that produces a lower overall cost. Either way it is spelled out up front, and we show you both options.
How does a mortgage broker get paid?
A broker is paid a set percentage of the loan amount, by either the lender or you, and by federal rule it must be disclosed and cannot change based on your loan terms. Because we earn the same regardless of which lender you choose, our incentive is to find the best-fit loan, not to steer you.
Mortgage broker vs. bank in Chicago: which is better?
A broker shops many wholesale lenders for one file, while a bank offers only its own products. For Chicago's mix of condos, two-flats and self-employed buyers that range matters, because one bank's single guideline box can decline a file another lender would approve. A bank can still win on a plain-vanilla file, which is why we compare honestly.
What should I ask a Chicago mortgage broker before working with them?
Ask how they are paid, how many lenders they actually work with, whether they are licensed in Illinois, and how they handle Chicago-specific issues like condo warrantability and Cook County taxes. You should get clear, specific answers, and we put ours in writing.
Is it worth using a mortgage broker?
For most Chicago buyers, yes, especially with a condo, a 2-4 unit, less-than-perfect credit, or self-employment income. A broker's value is matching your specific file to the lender most likely to approve it at the best price, which is hardest exactly where Chicago's housing stock is most varied.
Can you negotiate your mortgage rate?
Your rate is not a single sticker price; it moves with your credit, down payment, loan amount, property type and points. A broker effectively negotiates by pricing your file across many lenders at once and showing you the rate-versus-points trade-offs, so you buy the rate down only when it pencils out for how long you will keep the loan.
How much does a mortgage broker cost in Chicago?
Broker compensation generally runs about 1 to 2% of the loan amount and is disclosed on your Loan Estimate. When it is lender-paid it is built into the rate rather than charged at closing; when it is borrower-paid you will see it as a line item, and we show which option nets the lower overall cost.
Do mortgage brokers get better rates than banks?
Often, because a broker accesses wholesale pricing from many lenders and can place your file with whichever one prices your scenario best that day. There is no guarantee a broker always beats a given bank, so we compare your real options side by side instead of promising a headline number.
Will shopping with a mortgage broker hurt my credit?
A single rate-shopping credit pull has a small, temporary effect, and multiple mortgage inquiries within a short window (typically 14 to 45 days) are scored as one, so shopping responsibly does not stack up damage. You can also get a real rate from us first with no credit pull.
Can a mortgage broker help if I am self-employed?
Yes, and it is one of the biggest reasons to use a broker in Chicago. We work with lenders that understand self-employed income, including bank-statement and other alternative-documentation programs, so a tax return that understates your real cash flow does not automatically sink your approval.
Is a mortgage broker licensed and regulated?
Yes. Illinois mortgage brokers and their loan officers are licensed through the NMLS (Nationwide Multistate Licensing System) and regulated at the state and federal level. You can verify any broker or officer by name or NMLS ID on NMLS Consumer Access before you work with them.
How long does it take to close with a broker in Chicago?
Most Chicago purchase loans close in about 30 days, though condo document reviews or appraisal timing can shift that. We tell you up front what your specific file needs and keep the timeline realistic, which matters when your offer promised a closing date.
Have a Chicago question we didn't cover?Condo, two-flat, self-employed, or tax questions — get a straight answer, usually same day
Today's sample Chicago rates are shown live above, updated November 18, 2026 from our own pricing engine. Your actual rate depends on your credit, down payment, loan program and property type, so price your exact scenario in the calculator with no credit pull.
Is there a good mortgage broker near me in Chicago?
Yes. Gateway Capital Mortgage serves buyers and homeowners across Chicago and the near suburbs, from Lincoln Park and Logan Square to Beverly and Oak Park, and you can get a real rate and talk to a licensed loan officer the same day without visiting an office. We shop many wholesale lenders for your file instead of offering one bank's single product.
What should I look for in the best Chicago mortgage broker?
Look for a broker who shops many lenders, prices Chicago property types correctly, and has verifiable credentials and reviews. Gateway Capital Mortgage is NMLS-licensed and BBB A+ accredited, rated 4.9 stars across 310+ reviews, and specializes in Chicago condos, two-flats and self-employed files so the loan is matched to your property and your income.
What is the 2026 conforming loan limit in Cook County?
For a one-unit home it is $832,750 in 2026. FHA is set lower at $541,287. Above the conforming limit you are in jumbo territory, which we also handle.
Can you finance a Chicago condo, even a non-warrantable building?
Often yes. A building's warrantability, reserves, owner-occupancy ratio and any special assessments all affect the loan, and we work with lenders that handle both warrantable and non-warrantable buildings. We can help you read a building's financials before you commit.
How does buying a Chicago two-flat or three-flat work?
You can often use the expected rental income to help you qualify, and by living in one unit you can buy with owner-occupied financing, including low-down-payment options, while tenants help cover the mortgage. We set up this house-hack strategy regularly and get the rental-income calculation right.
How much are Chicago property and transfer taxes?
Illinois runs roughly a 2.08% effective property-tax rate, among the highest in the country, and Chicago charges a real property transfer tax at closing. Homeowner exemptions lower the bill on a primary residence, and we build a realistic tax figure into your qualification so nothing surprises you.
What help is there for first-time buyers in Chicago?
FHA, low-down-payment conventional, and Illinois (IHDA) and city down-payment-assistance programs are all in play, often paired with a condo or two-flat as the entry point. We price the options side by side and show the real monthly payment and cash to close.
Talk to a broker who knows Chicago
Price a Chicago loan in about thirty seconds with no credit pull, or send us your scenario, condo, two-flat, and tax questions included, and get a straight answer, usually the same day.
We are very grateful to the team for helping us get across the finish line and into our first home! Throughout the process they worked hard to earn our business and followed through on every promise. They put together a very competitive loan for us. I especially want to recognize our loan processor, who was absolutely amazing from start to finish: responsive, organized, and patient. As first-time homebuyers we had an endless number of questions, and she answered every single one without ever making us feel like a bother. She kept everything on track and helped us close on time. The team even sent a thoughtful closing gift. Thank you all for helping us become homeowners!
B
Brandon P ✔
September 1, 2026
BBB
★★★★★
Have closed 2 separate homes with Gateway Capital. Very professional and friendly in both transactions. Will continue to be my go-to lender.
C
Christian K ✔
August 25, 2026
BBB
★★★★★
Great experience, over delivered on rates and speed of underwriting. Would highly recommend.
A
Andrew T ✔
August 7, 2026
BBB
★★★★★
I had a great experience working with the Gateway team. They were extremely helpful during the process and guided me through some key decisions. I will gladly work with them again in the future.
R
Raj U ✔
August 7, 2026
BBB
★★★★★
Five stars for Gateway Capital Mortgage. After working with them on a few recent investment properties, they have become my go-to for mortgage lending. Incredibly communicative, always available to run numbers or check current rates when I'm evaluating a new property, and they navigate the paperwork effortlessly. If you want a seamless closing process, work with Gateway.
M
mikeb ✔
Saint Petersburg, FL · March 24, 2026
Zillow
★★★★★
Best mortgage broker
Michael and the team at Gateway Capital provide a fantastic, professional service for homebuyers. As a first-time home buyer, Michael was very patient, always available, and expertly informative. He helped us secure an excellent mortgage package, and we were cleared to close ahead of schedule. 5 stars in every way.
Z
Zafar Mahmood ✔
Wylie, TX · March 21, 2026
Zillow
★★★★★
Great refinance experience
I have just refinanced with Gateway Capital Mortgage and it has been an incredible experience. Michael Tadros helped me lock the lowest rate possible, him and his entire team worked tirelessly to make it the best refinance in a short amount of time. Michael and team were on top of all aspects to close in just 16 days for me!
E
Ethan ✔
Lewisville, TX · March 19, 2026
Zillow
★★★★★
Great service, direct information
I shopped around pretty seriously and Gateway Capital Mortgage came in with the best rate without the extra points stuff. On top of that the customer service from Michael and his team was top tier. Will be using them again next time!
O
Olivia N ✔
Eglin AFB, FL · November 17, 2024
Zillow
★★★★★
Solid rate, flexible, quick closing
Michael and the team at Gateway Capital Mortgage were fantastic to work with! The sellers were difficult, which drove a lot of changes to closing, but the GCM team was professional, flexible, and got us to the finish line!
M
miguelmhb79 ✔
Decatur, TX · October 16, 2024
Zillow
★★★★★
Great
Team was great, very helpful. Michael and Julie were great to work with. Very happy with their help. Thank you all, keep up the good work.
Garry Wheeler ✔
4 weeks ago
Google
★★★★★
A great team to work with from start to finish. I highly recommend them.
Devin McDermott ✔
a month ago
Google
★★★★★
We had an incredible experience with Gateway Capital Mortgage during our first time home buying process! Sean and the team were so helpful and detail-orientated! We ended up closing in 3 weeks and they played a major part in making that happen.
Jane Doeva ✔
a month ago
Google
★★★★★
Gateway Capital Mortgage provided exceptional service! Michael contacted me immediately and gave me a clear list of documents needed for pre-approval. Once I was approved for the full amount requested, the entire process took less than a month to close. I highly recommend this company—especially if you are financing a modular/mobile home, which can be incredibly challenging when dealing with traditional banks.
Gil L'Hommedieu ✔
a month ago
Google
★★★★★
Michael and his team are the Real Deal. Michael even took my call on a Sunday morning. He and his team worked hard to secure the best possible rate and terms while getting me to the closing table fast. They've absolutely earned my future business and this endorsement.
Debra Allen ✔
a month ago
Google
★★★★★
Everyone was very helpful and a pleasure to deal with throughout the entire process, including post-closing. They also offered the lowest rate so it was a win win!
We are very grateful to the team for helping us get across the finish line and into our first home! Throughout the process they worked hard to earn our business and followed through on every promise. They put together a very competitive loan for us. I especially want to recognize our loan processor, who was absolutely amazing from start to finish: responsive, organized, and patient. As first-time homebuyers we had an endless number of questions, and she answered every single one without ever making us feel like a bother. She kept everything on track and helped us close on time. The team even sent a thoughtful closing gift. Thank you all for helping us become homeowners!
B
Brandon P ✔
September 1, 2026
BBB
★★★★★
Have closed 2 separate homes with Gateway Capital. Very professional and friendly in both transactions. Will continue to be my go-to lender.
C
Christian K ✔
August 25, 2026
BBB
★★★★★
Great experience, over delivered on rates and speed of underwriting. Would highly recommend.
A
Andrew T ✔
August 7, 2026
BBB
★★★★★
I had a great experience working with the Gateway team. They were extremely helpful during the process and guided me through some key decisions. I will gladly work with them again in the future.
R
Raj U ✔
August 7, 2026
BBB
★★★★★
Five stars for Gateway Capital Mortgage. After working with them on a few recent investment properties, they have become my go-to for mortgage lending. Incredibly communicative, always available to run numbers or check current rates when I'm evaluating a new property, and they navigate the paperwork effortlessly. If you want a seamless closing process, work with Gateway.
B
Brent S ✔
July 23, 2026
BBB
★★★★★
As a first-time homebuyer I had many questions throughout the mortgage process, and Gateway Capital Mortgage consistently provided the guidance I needed. Their team was professional, courteous, and transparent from start to finish. They took the time to explain each step, answered my questions promptly, and made sure I had all the necessary documentation prepared for closing. I would recommend them to others, especially first-time buyers.
S
Steph V ✔
July 21, 2026
BBB
★★★★★
The team was great to work with and made the process as straightforward as possible for me. Everyone was kind and thoughtful, and I would definitely work with them again!
J
Jasmeet S ✔
July 17, 2026
BBB
★★★★★
Very nice people to talk to and communicate with throughout the process.
C
Cecilia B ✔
June 25, 2026
BBB
★★★★★
The team is excellent. They are honest, committed, and responsible. They are knowledgeable and guide you all the way through the process. Best interest rate in the market.
I
Inna D ✔
May 11, 2026
BBB
★★★★★
Gateway Capital Mortgage was a pleasure to work with from approval through closing. They were always easy to reach, professional, and great to work with throughout the entire process. Highly recommend!
M
mikeb ✔
Saint Petersburg, FL · March 24, 2026
Zillow
★★★★★
Best mortgage broker
Michael and the team at Gateway Capital provide a fantastic, professional service for homebuyers. As a first-time home buyer, Michael was very patient, always available, and expertly informative. He helped us secure an excellent mortgage package, and we were cleared to close ahead of schedule. 5 stars in every way.
Response from Gateway Capital MortgageThank you so much for the kind words, it truly means a lot. Helping first-time homebuyers navigate the mortgage process is something we take great pride in at Gateway Capital Mortgage, and I'm glad we could make the experience smooth, informative, and stress-free for you. Clear communication, competitive mortgage options, and on-time closings are always our priority. Wishing you many happy years in your new home.
Z
Zafar Mahmood ✔
Wylie, TX · March 21, 2026
Zillow
★★★★★
Great refinance experience
I have just refinanced with Gateway Capital Mortgage and it has been an incredible experience. Michael Tadros helped me lock the lowest rate possible, him and his entire team worked tirelessly to make it the best refinance in a short amount of time. Michael and team were on top of all aspects to close in just 16 days for me!
Response from Gateway Capital MortgageThank you, Zafar! It was truly a pleasure helping you refinance your home in Wylie. I'm glad our team was able to deliver a quick 16-day closing and exceed your expectations on both interest rate and closing costs. We appreciate your trust and look forward to assisting you, or anyone you refer, with future home loan needs.
E
Ethan ✔
Lewisville, TX · March 19, 2026
Zillow
★★★★★
Great service, direct information
I shopped around pretty seriously and Gateway Capital Mortgage came in with the best rate without the extra points stuff. On top of that the customer service from Michael and his team was top tier. Will be using them again next time!
Response from Gateway Capital MortgageEthan, thank you so much for the kind words and for trusting Gateway Capital Mortgage with your home financing. It means a lot to hear that you felt well-supported throughout the process. We truly appreciate the opportunity to help with your mortgage in Lewisville and look forward to assisting you again on your next home purchase or refinance.
Y
Yordan R ✔
June 30, 2025
BBB
★★★★★
Great customer service. Very easy to keep in touch with. Helped me choose the best mortgage with the best terms.
Response from Gateway Capital MortgageDear Yordan, thank you so much for your fantastic review! We're thrilled you had a great experience with our customer service and found it easy to stay in touch. Helping you choose the best mortgage with the best terms is exactly what we aim for. We truly appreciate your business!
O
Olivia N ✔
Eglin AFB, FL · November 17, 2024
Zillow
★★★★★
Solid rate, flexible, quick closing
Michael and the team at Gateway Capital Mortgage were fantastic to work with! The sellers were difficult, which drove a lot of changes to closing, but the GCM team was professional, flexible, and got us to the finish line!
Response from Gateway Capital MortgageHi Olivia, thank you so much for your kind review! We're thrilled to hear that Michael and our team were able to support you through a challenging process. It was a pleasure helping you secure your new home. Congratulations on your new home!
M
miguelmhb79 ✔
Decatur, TX · October 16, 2024
Zillow
★★★★★
Great
Team was great, very helpful. Michael and Julie were great to work with. Very happy with their help. Thank you all, keep up the good work.
Response from Gateway Capital MortgageThank you so much for the kind words and for trusting Gateway Capital Mortgage with your refinance. We're thrilled to hear Michael and Julie were able to make the process smooth, helpful, and timely from start to finish. We truly appreciate your support.
J
James Speights ✔
Richardson, TX · September 25, 2024
Zillow
★★★★★
Helpful
Michael explained everything thoroughly and the home buying process went smoothly. If I later decide to refinance my mortgage, I will definitely talk to GCM again first.
Response from Gateway Capital MortgageHi James, thank you for taking the time to share your experience with Gateway Capital Mortgage! We're delighted to hear that Michael provided thorough explanations and that your home buying process went smoothly. Congratulations on your new home!
K
Katie Welp ✔
Odessa, FL · September 3, 2024
Zillow
★★★★★
5 stars
Michael and team were exceptional to work with. He's great with communication and cares about his clients and that is very clear in the support he provides. The experience working with Michael and Gateway was top notch. Great people and well run business. I highly recommend them!
Response from Gateway Capital MortgageHi Katie, thank you so much for taking the time to leave us such a wonderful review. We're thrilled to hear that your experience with Michael and the Gateway team was top-notch. Your kind words mean a lot to us.
S
Simon B ✔
August 1, 2024
BBB
★★★★★
I've been working with the Gateway team to finance a single-family residence. The service and guidance I received were beyond my expectations. We were able to close within 21 days! I will definitely be coming back in the future with my real estate financing needs.
Response from Gateway Capital MortgageThank you so much for your kind words! We're thrilled that Michael and Julie were able to provide exceptional service and that you closed so quickly. We're excited to assist with your future real estate financing needs.
A
Andrew Bishay ✔
Orlando, FL · July 10, 2024
Zillow
★★★★★
Saved me thousands!
I reached out to Gateway Capital after already working with another mortgage company who vowed I was getting the best deal on this planet. But after a weird feeling I started noticing a few red flags, so I shopped, and by the grace of God I found Mike Tadros.
Response from Gateway Capital MortgageHi Andrew, thank you so much for sharing your experience with Gateway Capital Mortgage! We're thrilled that Mike Tadros and our team were able to provide such a positive outcome. Saving nearly $10,000 on fees is no small feat, and we're delighted we could help make your home buying process easier. Congratulations on your new home!
A
Andrew B ✔
July 10, 2024
BBB
★★★★★
I reached out to Gateway Capital after already working with another mortgage company who vowed I was getting the best deal on the planet. After a weird feeling I started noticing red flags, so I shopped, and thankfully I found Gateway Capital. They confirmed my suspicions and knocked it out of the park, doing everything the other company promised plus saving me nearly $10k in fees. It could not have been easier or more pleasant. Thank you for getting me into my new home.
K
Kevin B ✔
Cape Coral, FL · July 8, 2024
Zillow
★★★★★
Fantastic Company
If you're considering using Gateway Capital Mortgage, I HIGHLY recommend this company. They are on top of it and a class act. Very professional and informative, always in communication and determined to get the job done. I couldn't be happier I found them.
Response from Gateway Capital MortgageHi Kevin, thank you for your glowing recommendation of Gateway Capital Mortgage! We're thrilled to hear about your positive experience with our services. Your recommendation means a lot to us, and we look forward to assisting your friends and family in the future.
K
Kevin B ✔
July 8, 2024
BBB
★★★★★
I had a great experience working with Gateway Capital Mortgage to secure a home loan. If you're doing your research and considering them, I HIGHLY recommend them. They made what can be a very challenging process not so challenging. Michael and Julie were always in communication, answered any questions I had, and really got the job done. I'm so happy I came across this company and will be referring friends and family.
D
Dylan C ✔
July 5, 2024
BBB
★★★★★
I could not be happier with the level of service I received from Gateway Capital. From the team connecting all the dots and tirelessly answering my many questions, to patiently walking me through my insurance options, they surpassed our expectations. Even when the appraisal caused a significant bump in the road, they made the deal happen on budget and on time. I'm very glad I chose Gateway Capital and would recommend them without hesitation.
Response from Gateway Capital MortgageDear Dylan, thank you so much for your glowing review! We're thrilled to hear about your positive experience with our team. Navigating mortgage and insurance options can be daunting, and we're delighted we could assist you so effectively. We truly appreciate your recommendation and trust in Gateway Capital Mortgage.
K
kayla ✔
Naperville, IL · June 11, 2024
Zillow
★★★★★
10/10 Recommend
Mark was absolutely amazing throughout the entire home buying process. As this was my first home, I was concerned as I didn't know what to really expect. Mark explained everything thoroughly and answered every single one of my many questions. Mark truly cares about who he is working with.
Response from Gateway Capital MortgageThank you so much Kayla! You were amazing to work with and wish you many happy and blessed days in your new home.
Mike Tadros and his Gateway Capital Mortgage team have no equal in the mortgage business. They are by much the best. Mike is always there to answer your questions and help you to have the best deal possible.
Response from Gateway Capital MortgageIt's wonderful to hear such high praise for Mike Tadros and his team at Gateway Capital Mortgage! Mike's dedication to answering questions, ensuring the best deals, and maintaining excellent manners speaks volumes about his professionalism. Thank you for sharing your positive experience!
A
Alicia H ✔
March 20, 2024
BBB
★★★★★
Our loan officer was nothing short of fantastic to work with! She worked quickly and always looked out for our best interest to get us our dream home. We don't plan to move ever again, but Gateway will be our first recommendation for a mortgage lender.
Response from Gateway Capital MortgageThank you so much for your glowing review and for recognizing our team's dedication and professionalism! We're thrilled we could go above and beyond to ensure a seamless and efficient mortgage process for you. We truly appreciate your recommendation.
F
Fernando Reyes ✔
McAllen, TX · December 13, 2023
Zillow
★★★★★
Thank God I met Gateway Capital
This is my first time buying a home. I already had a lender, but I had a gut feeling not all was right. He had me on a down payment assistance program at 8.25%, and this was after I had already given $23,500 to the builder.
Response from Gateway Capital MortgageThank you so much Fernando! You are an amazing client, and I am so glad I was able to be a part of your first-time home buying experience.
S
shahriarpriang ✔
Fort Myers, FL · December 13, 2023
Zillow
★★★★★
Helpful
I just closed my loan with Mark. I couldn't be happier. I worked with a couple of other lenders but with Mark it was easy. He is so helpful and informative throughout the loan process. I would definitely recommend.
Response from Gateway Capital MortgageThank you for your trust and confidence.
A
amy19930 ✔
Mineola, TX · August 10, 2023
Zillow
★★★★★
Great customer service
My husband and I had a great experience with Gateway Capital Mortgage. Mark and Nicole were very helpful and responsive and answered every question we had during the process of the loan. They made the process easy and fast, we closed 1 week early.
Response from Gateway Capital MortgageIt was a pleasure working with you also. Thank you!
S
SamanthaCosner ✔
Saint Petersburg, FL · August 4, 2023
Zillow
★★★★★
Super easy process
Super easy to work with, answered every dumb and smart question I had along the way in a very timely manner. Kaleb got things done and I'm so grateful. Super easy process with his help.
N
nagar7294 ✔
Tampa, FL · July 26, 2023
Zillow
★★★★★
Best lender ever
Mark was on top of everything from the moment we needed the preapproval letter. We got the house we always wanted thanks to him and his responsiveness. 2nd house we did with him this year and hopefully many more. Thank you!
Response from Gateway Capital MortgageThank you so much for your kind words. Really enjoyed working on this for you.
F
F. Haddad ✔
Sunrise, FL · June 5, 2023
Zillow
★★★★★
Amazing rates and knowledgeable team
Gateway Capital Mortgage and their team were an absolute pleasure to deal and work with. This will be the 6th mortgage that I've used them for; three home purchases and three refinances.
Response from Gateway Capital MortgageDear Mr. Haddad, thank you so much for sharing your positive experience with Gateway Capital Mortgage. We are delighted that our team has consistently provided excellent service throughout your six mortgage transactions. Your satisfaction and trust are our top priorities.
K
Ken Ward ✔
Wimauma, FL · June 2, 2023
Zillow
★★★★★
A true professional and an advocate
My wife and I just closed on a home purchase using Mark Halim at Gateway Capital Mortgage. This was a somewhat complex train of events involving four closings. All went well, but not without a few unexpected challenges that Mark handled expertly.
R
Russell May ✔
Apollo Beach, FL · May 16, 2023
Zillow
★★★★★
Amazing team!
The Gateway Capital Mortgage team were amazing to work with. We were looking to buy right when there were some issues in the banking world, but despite the uncertainty Michael was very transparent and upfront with all our options.
Response from Gateway Capital MortgageThank you for sharing your positive experience with Gateway Capital Mortgage! We're delighted the team, especially Michael, provided excellent service during a challenging time. We appreciate your recommendation and look forward to assisting you in the future.
K
Kayden Van ✔
Port Saint Lucie, FL · May 11, 2023
Zillow
★★★★★
Best lender
It was a pleasure to have Mark Halim working on our loan. This was me and my wife first time home buyers, and with Mark every step and application was easy. He kept us updated on everything and kept in touch with us.
Response from Gateway Capital MortgageThank you for the kind words and I appreciate you giving me the opportunity to assist you.
N
Nicole Jones ✔
Daytona Beach, FL · May 8, 2023
Zillow
★★★★★
Amazing and very helpful
Chris was amazing to work with. It was really wonderful to feel like someone you just met felt so much like a partner. He helped me with all of my questions, and put forth the effort needed to close in 20 days.
Z
Ziba Mohammadi ✔
Saint Petersburg, FL · March 16, 2023
Zillow
★★★★★
Reliable and honest lender
Nevene introduced my family and me to a great mortgage program that I could not get from anyone else. She is my go-to person. We will close our next mortgage with her as well.
D
David crader ✔
Tampa, FL · March 13, 2023
Zillow
★★★★★
Great lender
Enjoyed working with Kaleb. Always fast to respond and a good work ethic. Ended up coming in with a better rate than many competitors and was happy to go with his product.
C
carlos3336 ✔
Palm Bay, FL · February 28, 2023
Zillow
★★★★★
A lender that thinks outside the box
It was a pleasure to deal with Gateway and Mark specifically. He was responsive and professional throughout the entire process. Most important for my situation as a self-employed business owner was his ability to think outside the box.
M
Marie ✔
Saint Petersburg, FL · January 26, 2023
Zillow
★★★★★
Helpful as a lender and a Realtor
Kaleb was very helpful in our house buying process, giving us various mortgage options according to what we requested. He was always quick to reply to our questions. We finally got our mortgage through Kaleb.
D
Dan Eliopulos ✔
Lemont, IL · December 1, 2022
Zillow
★★★★★
Quick to act in a challenging market
I worked with Mark for the last 2 months on securing a mortgage while rates were at all-time highs. Mark was very transparent with the current situation and was able to provide me the best rate in a challenging time.
L
luke3174 ✔
Saint Petersburg, FL · October 25, 2022
Zillow
★★★★★
Great guy to work with!
Kaleb helped me get into my first house when I wasn't confident I would qualify. He has great understanding of the mortgage process, is straight forward and very helpful. I would recommend him to family and friends.
Response from Gateway Capital MortgageThank you Luke! I enjoyed working with you and your referrals!
J
John C. ✔
Largo, FL · October 25, 2022
Zillow
★★★★★
Outstanding guidance and assistance
Kaleb really helped me land a mortgage that worked for me. We walked through my monthly income and expenses to build a budget and determine how large of a mortgage I could carry and still live life on my terms.
Response from Gateway Capital MortgageThank you John! I appreciate your business and look forward to more in the future!
R
Rosalina Luis ✔
Sunrise, FL · June 28, 2022
Zillow
★★★★★
Professional and helpful
Mark and his team were very professional and helpful during our loan process. The process was complex due to a 1031 exchange. I highly recommend him and his team.
V
Verified Zillow reviewer ✔
Dade City, FL · March 29, 2022
Zillow
★★★★★
Transparent, professional, and highly efficient
Transparent, professional, and highly efficient are the words I would use to describe my experience with Mark. From the very beginning he was crystal clear about every aspect of the loan, and the document requirements were submitted in a timely manner.
V
Verified Zillow reviewer ✔
New Port Richey, FL · January 16, 2022
Zillow
★★★★★
Highly recommended
My wife and I recently closed on a home purchase in Pasco County, FL and we could not be happier with the service and results we received from Mark Halim and his team at Gateway Capital Mortgage. From start to finish, Mark was friendly, transparent and informative.
J
J Penrow ✔
Evans, GA · August 25, 2021
Zillow
★★★★★
Great customer service!
Mark was great and very professional and took care of everything. My case was a little tricky because I had a lien on my house that had to be paid before refinancing, and Mark got this included in the refinance.
R
Ray Ballantine ✔
Joliet, IL · April 27, 2021
Zillow
★★★★★
Saved $10,000 with Gateway
Mark is a professional in what he does for home owners on refinancing. He is great and has saved me plenty of money. He did 3 VA refinances with me and completed them in record time.
M
Max ✔
Plainfield, IL · April 11, 2021
Zillow
★★★★★
Excellent service with GCM
I had a great experience working with Mark Halim and his team at Gateway Capital Mortgage. This was, by far, the easiest and least expensive refinance I've ever done. I highly recommend this lender if anyone is looking to refinance!
M
Michael B ✔
Stoughton, WI · March 4, 2021
Zillow
★★★★★
A pleasure to work with!
Very efficient, answered all my calls, got the job done. Would definitely use again. From the first phone call, we got it locked in soon after with a great rate.
A
adamali60602 ✔
Chicago, IL · February 28, 2021
Zillow
★★★★★
Easy and best experience
Chris and Jill helped me refinance 2 loans at the same time. Got me an exceptional rate and he was always so detailed with his emails and took the time to communicate effectively.
J
jkoudelik ✔
Naperville, IL · February 19, 2021
Zillow
★★★★★
Made our home buying experience less stressful
Mark did a wonderful job handling the mortgage on our new home purchase. He followed up and responded to questions quickly. Thank you Mark and Gateway for being our responsive advocate.
M
Michael ✔
Moorhead, MN · December 16, 2020
Zillow
★★★★★
Great to work with
Chris was there every step of the way and was able to answer all of my many questions. A lot of people have been trying to refinance right now and that didn't stop Chris from being available to answer my questions.
S
Sharon ✔
Colorado Springs, CO · October 7, 2020
Zillow
★★★★★
Second time around
We had such a good experience the first time we used GWC to refinance our vacation home, so we didn't hesitate to contact them again to refinance our primary home.
T
Tim ✔
Hollywood, FL · September 30, 2020
Zillow
★★★★★
Excellent service, highly recommend!
The entire team at Gateway Capital Mortgage was fantastic to work with, Mark and Julie in particular. Not only did everyone provide great service, but the advice and guidance along the way was extremely helpful.
G
Gerry Carroll ✔
Pompano Beach, FL · September 4, 2020
Zillow
★★★★★
Excellent experience
Mark was the ultimate professional throughout my refinance. Responded to emails very quickly and outside normal hours with clear and concise information.
M
Mitchell Thompson ✔
Delray Beach, FL · August 26, 2020
Zillow
★★★★★
Amazing experience
Chris and the team at Gateway Capital Mortgage were amazing from the beginning to the end. Chris was very responsive and kind throughout. Julie Cook also helped the process and she too was great to work with!
R
Ray Iris ✔
Saint Petersburg, FL · July 10, 2020
Zillow
★★★★★
Superb
Mark is simply incredible. This is the second time I have used Mark, once for the purchase of my first home and now for a refinance. Mark is great at what he does and is the easiest person to communicate with, day or night.
S
sayounie ✔
Saint Augustine, FL · June 26, 2020
Zillow
★★★★★
Exceptional service
Started with 2 other lenders before discovering Chris Rezk at Gateway Capital Mortgage to refinance our second home condo. With his wealth of knowledge and experience, Chris patiently answered every question we had.
D
Dan B ✔
Roswell, GA · June 10, 2020
Zillow
★★★★★
Great refi!
Mark and Julie at Gateway Capital Mortgage were fantastic and this was the easiest mortgage financing transaction I've ever experienced from start to finish. They helped me lock in at the right time.
M
Moe Aboutabl ✔
Naperville, IL · May 22, 2020
Zillow
★★★★★
Great experience
What a great experience. I'd like to start with a thank you to my loan officer Mark Halim for making the entire process from start to finish seamless and better than expected.
S
sbfoisy ✔
Evanston, IL · May 20, 2020
Zillow
★★★★★
A pleasure!
Mark Halim was a pleasure to work with! He was always available and so knowledgeable. You felt like you were his only customer. During a stressful time, Gateway did everything in their power not to make this another stressful experience!
L
Lara2288 ✔
Wheaton, IL · March 9, 2020
Zillow
★★★★★
Top notch
Mark came highly recommended to us and we quickly came to understand why. He was highly responsive and worked diligently to make things happen for us. I still can't believe how fast we closed.
C
Christopher Pecoraro ✔
Winter Park, FL · October 21, 2019
Zillow
★★★★★
Great company, great people
Mark Halim was extremely efficient and helpful in answering all of my questions and navigating through our history to put together our approval paperwork.
N
Nilied Baez ✔
Saint Pete Beach, FL · October 8, 2019
Zillow
★★★★★
Five star representative!
Mark is an extremely prepared professional that took service to another level. He was with us in all steps of the process. Very knowledgeable and patient. He answered all our calls, emails and texts, no matter what time it was.
A
Alfredo ✔
Tampa, FL · June 4, 2019
Zillow
★★★★★
Smooth
They followed up on every single detail to make sure the application went through. They also provide assistance based on your requests to maximize your benefits with the mortgage. Thank you!
M
M. Coffman ✔
Saint Petersburg, FL · November 13, 2018
Zillow
★★★★★
Outstanding service
Michael and his team were phenomenal to work with. Outstanding customer service throughout the entire process. Very thorough and proactive. Would highly recommend them for all your condo financing needs.
Response from Gateway Capital MortgageThank you for the thoughtful review and for trusting Gateway Capital Mortgage with your condo purchase in Saint Petersburg. Helping clients navigate condo financing and secure the right mortgage solution is something we take great pride in.
R
rajavimal ✔
Davie, FL · September 25, 2018
Zillow
★★★★★
Amazing response, competitive rate
I recently used the service from the firm and I have to really appreciate and am amazed with their knowledge in the field and the responses. Personally I had a wonderful experience working with Chris. He is amazing and very easy to deal with.
B
Barbara Nieves ✔
Tampa, FL · September 16, 2018
Zillow
★★★★★
Excellent!
Mark Halim did such an excellent job with my home loan process. I was so amazed how quickly my home was approved. It took only 1 week to receive an approval. Mark gave me a great interest rate.
Response from Gateway Capital MortgageThank you for taking time out of your busy day to write that great review. It was a pleasure working with you on the loan.
B
Bob Bender ✔
Oldsmar, FL · July 25, 2018
Zillow
★★★★★
Home purchase
Mark was extremely helpful and educated us on Florida procedures. He answered all questions promptly and helped us secure the right answers. We were very pleased with his help as well as Julie's.
R
roylh1 ✔
Lake Placid, FL · May 15, 2018
Zillow
★★★★★
Gateway Capital Mortgage review
My husband and I were very pleased with Gateway Capital Mortgage and especially Mark Halim. Mark walked us through every part of the process and he was always pleasant and had all the answers.
B
Brannan ✔
Cape Coral, FL · April 27, 2018
Zillow
★★★★★
Chris was amazingly outstanding
My husband and I just purchased a vacation home. Chris Rezk was very professional and knowledgeable in helping us with this purchase. Always responded quickly and did everything possible to make things happen.
A
Ana M. Gonzalez ✔
Hollywood, FL · April 2, 2018
Zillow
★★★★★
Excellent
I had the pleasure of working with Mark Halim, a trusted professional who treated me with the utmost respect from the first moment I applied. I was not a favorable candidate to embark on homeownership, or so I thought.
A
Ann ✔
The Villages, FL · February 27, 2018
Zillow
★★★★★
Excellent job
Worked with Mark Halim to refinance our home. He did an excellent job from start to finish. He answered all my questions and everything went along according to plan with no surprises.
D
diannesparks ✔
Boynton Beach, FL · February 23, 2018
Zillow
★★★★★
Michael Tadros
I got a recommendation to use Mike as my mortgage broker and there is no one out there that could have done a better job. Mike and his staff were extremely knowledgeable and attentive to all details in getting me the best lender.
Response from Gateway Capital MortgageThank you Dianne for the kind words. It was a real pleasure working with you.
S
Susana and Ron C. ✔
Clearwater, FL · January 24, 2018
Zillow
★★★★★
Best choice we could have made
We were first time home buyers and our realtor recommended a few brokers including Gateway. When I started working with Chris Rezk, I felt comfortable right away and he explained every step so clearly that I felt I could rely on him for everything.
Response from Gateway Capital MortgageSusana and Ron, thank you so much for the kind review! I'm grateful you decided to work with me, and it was a joy to witness your patience and persistence get rewarded in the end. Congrats new home owners!
R
rksmith122201 ✔
Mulberry, FL · January 15, 2018
Zillow
★★★★★
First time home buyer
This is the first time my wife and I have ever bought a home and Mark made it a great experience. He really did make the process as painless as possible and was there to help us each step of the way.
V
Verified Zillow reviewer ✔
Orlando, FL · January 10, 2018
Zillow
★★★★★
Great experience as a first time buyer!
As a first time home buyer I was naturally nervous about this process. Mark Halim was just great! He went out of his way to help me close on my townhome in under one month.
V
Verified Zillow reviewer ✔
Germantown, WI · December 5, 2017
Zillow
★★★★★
Fantastic experience!
I was a little skeptical to work with a company that was not truly local to me and that I had never heard of before. But after I spoke to Chris I decided to give Gateway Capital Mortgage a chance and I was not disappointed! They were very competitive.
Response from Gateway Capital MortgageBrad, thank you so much for taking the time to leave such a wonderful review. Our job is so much easier when we get the privilege of working with such responsive and pleasant clients as yourself.
C
Crystal Graika ✔
Juneau, WI · November 14, 2017
Zillow
★★★★★
Awesome
Jill was a wonderful person to help me with my loan. I had started working with Jill the year before, and once I found a different property she was there for me every step of the way.
K
kimchee069 ✔
Saint Petersburg, FL · November 5, 2017
Zillow
★★★★★
Great team, personalized service!
We were fortunate to have had Gateway Capital Mortgage recommended to us by our real estate agent. They were on top of everything from the outset and were in constant touch throughout the process of applying for and getting a loan.
J
jjdvorak88 ✔
Pardeeville, WI · September 22, 2017
Zillow
★★★★★
She is the best
She is willing to answer any questions that you have. She is always willing to help even after the loan process! This is the second time we've used Jill during our house buying process. Thanks again Jill!
L
Lana Huynh ✔
Panama City Beach, FL · September 21, 2017
Zillow
★★★★★
Closed within one month!
My friend recommended Charles to me and I'm glad to have him as my lender. As a 1st time home buyer, there were a lot of unknown obstacles but Charles was professional, knowledgeable and caring.
Response from Gateway Capital MortgageThank you for the kind words and congratulations on being a home owner! I truly enjoyed working with you.
C
cjhdriders ✔
Pardeeville, WI · September 6, 2017
Zillow
★★★★★
Extremely knowledgeable
Jill knows all the ins and outs of the different types of loans and how to get things done in a timely manner. Excellent person to work with, always very helpful and explains things.
A
ash thiede ✔
Westfield, WI · September 6, 2017
Zillow
★★★★★
Went above and beyond!
Jill was great to work with! We had some credit hurdles to get through and she went above and beyond to get us there! She worked closely with us every step of the way.
V
Verified Zillow reviewer ✔
Green Cove Springs, FL · July 13, 2017
Zillow
★★★★★
Great company and employees
Jill was wonderful to work with. She was very professional and pleasant and helped us through the whole process. She kept us organized with all the necessary, complicated paperwork. One of our best experiences applying for a mortgage.
Z
Zillow reviewer ✔
Green Cove Springs, FL · July 13, 2017
Zillow
★★★★★
Great company and employees
Chris was extremely professional and pleasant to work with and made it so easy to get through what is usually a very stressful process. He worked hard to get us the best possible mortgage to meet our needs.
Response from Gateway Capital MortgageThank you so much for taking the time to leave this review! You were both amazing to work with, and I'm very happy for you.
R
rmhalik ✔
Longboat Key, FL · June 3, 2017
Zillow
★★★★★
Gateway Capital Mortgage
It was a pleasure working with Chris Rezk and the Gateway Capital team. Chris and his team were very professional, knowledgeable, helpful, responsive and pleasant. I highly recommend Gateway Capital Mortgage.
Response from Gateway Capital MortgageThank you for the kind words! The pleasure was all mine. I wish you all the best in your new home!
I
Irene Varol ✔
Hollywood, FL · April 9, 2017
Zillow
★★★★★
Knowledgeable and professional
I am fully satisfied with the service from Gateway Capital. Charles Tadros walked me through the entire process. He was always available to answer any questions and alleviate any concerns.
Response from Gateway Capital MortgageMy pleasure! I hope you enjoy your new home!
A
anthonyc51 ✔
Western Springs, IL · April 5, 2017
Zillow
★★★★★
Refinance
Michael explained the process in great detail every step of the way. He made our refinance go as smooth as could be expected. I would definitely use him again.
D
dmcdonald018 ✔
Marco Island, FL · April 1, 2017
Zillow
★★★★★
Superior professional service
Charles walked me through the process step by step. He was very professional and conveyed a true sense of caring and trust. Will definitely use his services again.
Response from Gateway Capital MortgageThank you for the kind words and your business!
P
purpledawn1975 ✔
Saint Petersburg, FL · March 27, 2017
Zillow
★★★★★
Wonderful experience
Michael made the home buying experience a breeze. The team at Gateway was informative, always available for any questions or concerns, and made sure I knew everything upfront.
V
Verified Zillow reviewer ✔
Spring Hill, FL · March 23, 2017
Zillow
★★★★★
First time home owner
Nevene and her team did an outstanding job throughout the process of my home purchase! Nevene was always available when I had questions, and her team helped me all the way to my closing date. I highly recommend Gateway Capital.
R
rube8 ✔
Saint Pete Beach, FL · March 23, 2017
Zillow
★★★★★
Great experience with Gateway Capital
Last year we were looking to purchase our very first home and we had tons of questions, especially surrounding the financing part. We were introduced to Michael Tadros and his team at Gateway Capital Mortgage, and I am so glad they were part of it.
D
dasiy rosco ✔
Sarasota, FL · March 22, 2017
Zillow
★★★★★
Highly recommend
The whole experience from beginning to end with Nevene and her team was amazing. They explained the process every step of the way and were always helpful with every question I had.
T
tkosiek ✔
Wauconda, IL · March 22, 2017
Zillow
★★★★★
An expert with the heart of a teacher
I spend hours researching before making decisions, and a mortgage was no different. I asked Michael a million questions, and he took the time to teach me about the mortgage market.
M
mackinnon45 ✔
Pinellas Park, FL · March 22, 2017
Zillow
★★★★★
Very informative
I found Michael to be very informative and explained things well. Michael was able to help me find a much better rate when several other companies could not. I got the feeling he was working to benefit me, not himself.
L
lindamp63 ✔
Spring Hill, FL · March 22, 2017
Zillow
★★★★★
Everything went smoothly
Nevene and her staff were very helpful when helping us find our new home. The financing went fine, the closing went fine, everything went great. We would recommend her to anyone looking to buy a house.
C
cardinalseahawk ✔
Saint Petersburg, FL · March 21, 2017
Zillow
★★★★★
Wonderful first home buying experience
We are halfway through buying our first house and everything is going great! Michael is always there to answer my calls, texts and emails quickly when I start getting stressed.
A
AngelaSwartz ✔
Clearwater, FL · March 20, 2017
Zillow
★★★★★
Great experience from day one
As a first time home buyer Michael spent quite a bit of time with me explaining not only the process but the pros and cons of all my options. Communication was always present with quick responses, and it was very easy to get in touch.
E
Elizabeth Oakes ✔
Largo, FL · March 20, 2017
Zillow
★★★★★
Quick process
I was very satisfied with Gateway Capital Mortgage. Michael and his team made the process easy and helped answer questions quickly and thoroughly. I have used them for 2 of my mortgages in the last few years.
K
kportillo6 ✔
Mokena, IL · March 20, 2017
Zillow
★★★★★
Extremely easy
Gateway was so easy it made me feel like something wasn't right. I was approved really fast and they didn't ask for much info. Highly recommend them. Thanks!
G
gbuono8 ✔
Port Charlotte, FL · March 18, 2017
Zillow
★★★★★
Smooth refinance
Completely pleased with the service. Everything went as promised. His staff was very competent and easy to work with. I would definitely recommend his firm.
T
taylormgrover ✔
Saint Petersburg, FL · March 17, 2017
Zillow
★★★★★
Professionals who know the business
Michael Tadros and the team at GWC were very understanding of my home purchasing goals and of the financial constraints I had to work with. They set me up with a great rate and walked me through the entire process.
J
JANDLE1 ✔
Rockledge, FL · March 17, 2017
Zillow
★★★★★
Extraordinary results
I used Gateway Capital a year ago and just now. Both times the process was flawless and timely. My day-to-day bank was stunned at the terms; the closing costs were much lower and the rate better.
P
peterawad2001 ✔
Tarpon Springs, FL · March 17, 2017
Zillow
★★★★★
A professional in his job
He is a helpful person and a good advisor. He explained the process well to me and selected the best program and best interest rate for me.
V
Verified Zillow reviewer ✔
Seffner, FL · March 17, 2017
Zillow
★★★★★
Lender review
Michael was very helpful in answering all our questions throughout the lending process. He made us feel comfortable obtaining a loan through Gateway. We would recommend Gateway.
B
Bob Bartlett ✔
Lutz, FL · March 1, 2017
Zillow
★★★★★
Thank you
Nevene and everyone at Gateway Capital Mortgage was very helpful and informative. The whole process was great. I could not have asked for a better experience. I highly recommend Gateway Capital Mortgage!
A
averyww ✔
Plainfield, IL · August 5, 2014
Zillow
★★★★★
They stuck with us
My wife and I are pleased with the way Nevene Tadros handled the refinance of our home. It was a difficult roller coaster ride with my past credit, but Gateway Capital Mortgage stuck with us and pulled us through.
J
junkemailme247 ✔
Willow Springs, IL · August 5, 2014
Zillow
★★★★★
Saved us a fair amount
She did a great job for us. Always one step ahead, made the process really easy. She also did her homework and saved us a fair amount. Happy to recommend her to everyone we know.
Garry Wheeler ✔
4 weeks ago
Google
★★★★★
A great team to work with from start to finish. I highly recommend them.
Devin McDermott ✔
a month ago
Google
★★★★★
We had an incredible experience with Gateway Capital Mortgage during our first time home buying process! Sean and the team were so helpful and detail-orientated! We ended up closing in 3 weeks and they played a major part in making that happen.
Jane Doeva ✔
a month ago
Google
★★★★★
Gateway Capital Mortgage provided exceptional service! Michael contacted me immediately and gave me a clear list of documents needed for pre-approval. Once I was approved for the full amount requested, the entire process took less than a month to close. I highly recommend this company—especially if you are financing a modular/mobile home, which can be incredibly challenging when dealing with traditional banks.
Gil L'Hommedieu ✔
a month ago
Google
★★★★★
Michael and his team are the Real Deal. Michael even took my call on a Sunday morning. He and his team worked hard to secure the best possible rate and terms while getting me to the closing table fast. They've absolutely earned my future business and this endorsement.
Debra Allen ✔
a month ago
Google
★★★★★
Everyone was very helpful and a pleasure to deal with throughout the entire process, including post-closing. They also offered the lowest rate so it was a win win!